If you are a young entrepreneur hustling hard and making great money, grab a cup of coffee and sit down. We need to have a chill, but super important chat about your money. We see so many young people today doing amazingly well in business. You guys are smart, creative, and hardworking. Some of you […]
If you are a young entrepreneur hustling hard and making great money, grab a cup of coffee and sit down. We need to have a chill, but super important chat about your money.
We see so many young people today doing amazingly well in business. You guys are smart, creative, and hardworking. Some of you are selling out products on TikTok Shop every single day. Others are running aesthetic cafes, providing graphic design services, or dominating the Shopee marketplace.
Your monthly sales are off the charts. Some of you are hitting RM20,000, RM50,000, or even hundreds of thousands of ringgit in cash flow every single month!
Because the money is good, the lifestyle naturally upgrades. You swap your old car for a shiny imported ride. You wear branded clothes, and your Instagram looks absolutely incredible. But let us ask you one brutally honest question.
When you walk into a bank to apply for a financial loan or to buy your very first home, what usually happens?
The bank shakes their head, and you get that dreaded short answer: Application Rejected. Why does this happen? It is because you only have a strong bank statement, but zero solid financial foundation. You look wealthy on paper, but you hold zero physical assets.
This article is designed to change that. Let’s dive deep into why mastering Property Investment For Small Business Owners is your best move right now.
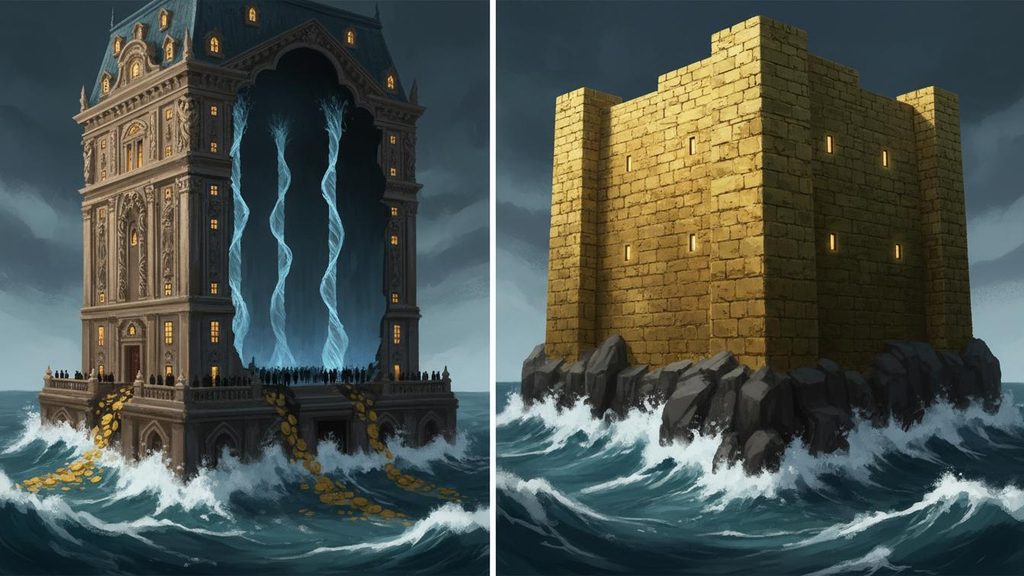
When we say you are “building a castle on the sand,” we are not trying to downgrade your hard work. We fully respect the sweat and tears you put into building your business from scratch.
However, there is a bitter truth in the business world that many young entrepreneurs completely miss. Online businesses and retail trends go up and down rapidly.
Today, your product might go viral and sell out in minutes. Tomorrow, the social media algorithm might change, and your sales could instantly drop to zero.
Today, customers might be obsessed with your brand. Next week, a brand new competitor could show up offering the exact same product for half the price.
The waves of the business ocean are always rough and unpredictable. Building a “castle on sand” means your business looks massive and successful from the outside, but it is completely unsupported by high-value, rock-solid assets.
If you do not funnel your business profits into real estate, you have absolutely zero safety net. Most young founders burn all their profits on rolling capital, paying for Facebook ads, and funding a luxurious lifestyle.
When an economic crisis hits or your business takes a massive hit, you have nothing to fall back on. That is why you need to convert your active cash flow into physical real estate as early as possible!
So, why is real estate the ultimate answer for business survival?
A house is much more than just a place to sleep. In the ruthless world of business, real estate is the most powerful survival tool you can own. You must shift your mindset today.
Here are four massive reasons why Property Investment For Small Business Owners is mandatory:
Let’s be real. When you want to expand your business and need a massive cash injection, the bank does not care about your TikTok followers.
Banks care about hard assets. They want to see collateral.
If you own a house or a commercial shop lot, you can pledge it to the bank. This allows you to unlock massive business credit facilities or low-interest business loans. Your property acts as your financial backup generator.
When you hustle in your business, you only make money when you work. But when you buy a rental property or a commercial space, it generates monthly rental income on autopilot.
This money flows right into your bank account without you having to spend a single cent on marketing or ads. It gives you peace of mind knowing that even if your shop has a slow month, your tenants are still paying you.
If you keep RM300,000 sitting in a regular bank account, inflation will slowly eat its value alive. Things get more expensive every year. Your cash is secretly losing its purchasing power.
But historically, real estate prices always go up over the long term.
That RM300,000 cash might feel like peanuts in ten years. But a RM300,000 property you buy today could easily explode to RM500,000 or more in the next decade!
Government servants have their guaranteed pensions. Corporate employees have their EPF (Employees Provident Fund). But what about you as a small business owner? Nobody is going to pay for your retirement.
Real estate is your true, self-made pension plan. When you are finally tired of the daily business grind, your fully paid-off properties will take care of you and your family for the rest of your life.
We completely understand your frustration. Business owners often face heavy discrimination from banks compared to 9-to-5 employees who have fixed monthly payslips.
Banks view entrepreneurs as “high-risk” individuals. But do not panic, there is a proven system to beat the bank at their own game. You just need to play by their rules. Let me break down the process into four incredibly easy steps:
This is the most basic rule. Your business must be officially registered. Whether it is a Sole Proprietorship, a Partnership, or an Sdn Bhd (Private Limited), it must be documented.
Never run an “underground” cowboy business! I trust you guys have already handled this step. For more details on proper registration, you can always check out the official Companies Commission of Malaysia (SSM) portal.
This is where many newbies fail. Never, ever use your personal savings account for business transactions! Every single cent of your business sales must go directly into an official company current account.
From that company account, you must pay yourself a fixed, consistent “salary” every single month into your personal account. Creating this clear paper trail is exactly how you prove your stability to the bank.
Ah, the taxman. This is the part where young entrepreneurs run away because they want to avoid paying taxes. Listen to me carefully: your tax receipt is the most valuable “love letter” you can give to a banker to get your home loan approved!
Banks do not trust your company bank statements alone because they know cash can be manipulated. They only trust the official income declaration you make to the government.
Money comes in ➔ You pay your salary ➔ You declare it via Form B ➔ The bank approves your loan!
You can manage all your tax filings through the LHDN Official Website.
Even as an entrepreneur, your personal credit score matters immensely. The bank will pull your CCRIS and CTOS reports to see how you behave with debt.
Keep your record sparkling clean. Do not miss a single payment on your credit cards or personal loans. A clean credit profile tells the bank that you are a highly responsible borrower.
When you finally submit your housing loan application to the bank officer, your documents must be perfect. If your paperwork is neat, organized, and complete, the banker will love you, and your approval process will be lightning-fast.
I have created a simple checklist of the mandatory documents you must prepare as a business owner:
| Type of Document | Duration / Specifics | Why The Bank Needs It |
| SSM Registration Certificate | Form D/E or Form 9, 24, 49 | Proves your business has existed legally for at least 2 years. |
| Company Bank Statements | Latest 6 to 12 Months | Shows the health of your cash flow and your ability to generate sales. |
| Personal Bank Statements | Latest 6 Months | Proves you receive a stable, consistent monthly salary from your business. |
| Form B / e-B (Tax Declaration) | Latest 2 Years | The ultimate official proof of your net income to the government. |
| Official Tax Receipts | Latest 2 Years | Proves you have cleared all your tax dues with zero outstanding balances. |
| Financial Statements / P&L | Profit & Loss and Balance Sheet | Gives a professional overview of your company’s financial health. |
| Photocopy of Identity Card (IC) | Front & Back clearly copied | Basic verification of the applicant’s identity. |
Think of these documents as your ammunition. If you go to war without bullets, you will lose. Start compiling these files immediately, aiming for a solid 2-year business track record.
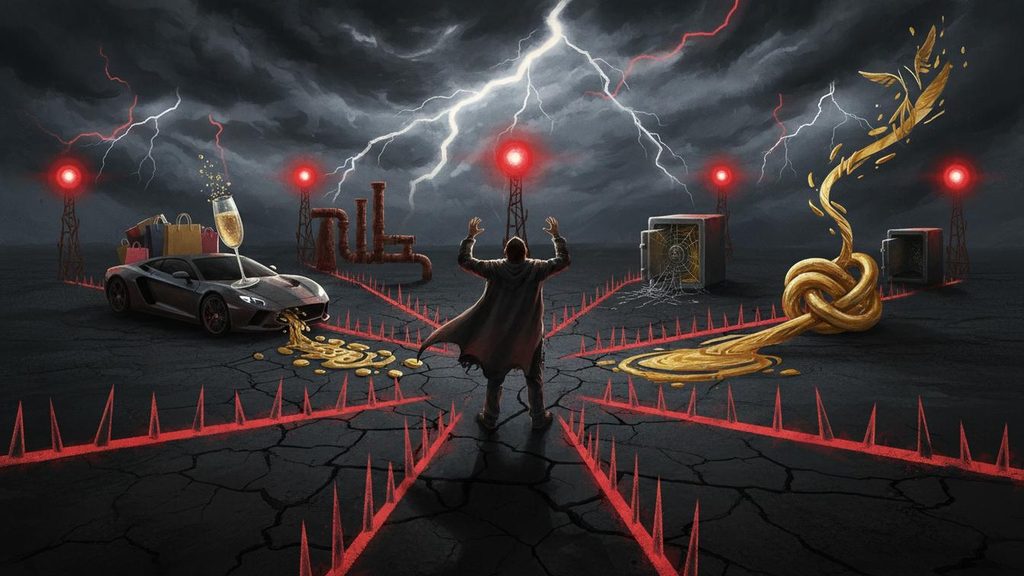
Based on my years of experience watching young people do business, there is a familiar pattern to financial failure. Usually, young business owners fall into the trap of thinking high gross sales equal pure wealth.
Let’s break down the deadliest mistakes so you can avoid them:
Buying personal clothes using the company debit card, or paying suppliers using your personal savings account. This creates a chaotic, messy audit trail. When bankers see this mess, they will instantly reject your loan. Keep it separate!
Your business makes a small profit, and suddenly you finance a brand-new imported car with a RM3,000 monthly commitment.
This completely destroys your Debt Service Ratio (DSR). When you try to buy a house later, you are already choked by your car debt. Buy the house first!
You think you are a genius for hiding your income and dodging taxes. But when you finally want to buy a property, absolutely no bank will lend you money because you have zero official proof of income. Pay your taxes, it is an investment in your future borrowing power.
Many newbies assume the bank loan will cover 100% of everything. Wrong! You still need hard cash for your 10% downpayment, legal fees, valuation fees, and stamp duties. Always save a chunk of your profits specifically for property acquisition.
Running a business is exhausting, guys. You squeeze your brain every day, manage stressful employees, and deal with difficult customers. Do not let years of your hard work vanish into thin air without building any permanent assets.
A castle built on sand will wash away the moment the economic waves hit. But an empire built on the solid ground of real estate will stand tall enough to protect your children and grandchildren.
Change the way you handle your business cash flow today. Organize your bank statements. Declare your taxes honestly. Pay yourself a fixed salary. And most importantly, start hunting for your very first real estate asset!
Remember this golden rule: High business sales make you look rich, but smart real estate investments make you truly wealthy.
What is Property Investment For Small Business Owners?
It is the strategic process where entrepreneurs use their business profits to purchase real estate (like houses, apartments, or shop lots). This strategy helps business owners build permanent wealth, secure passive rental income, and create a safety net against business failures.
Can a small business owner buy a house without a standard payslip?
Yes, absolutely! While you do not have an employer-generated payslip, you can prove your income to the bank using 6 months of company bank statements, your SSM registration, and most importantly, your declared LHDN income tax returns (Form B) for the past 2 years.
Why is property a better asset than keeping cash in a bank account?
Cash sitting in a bank account loses its purchasing power over time due to inflation. Real estate, on the other hand, historically increases in value (capital appreciation) while also allowing you to collect monthly passive income through rent.
What is DSR and why is it important for entrepreneurs?
DSR stands for Debt Service Ratio. It is a calculation banks use to see how much of your monthly income goes toward paying off debts. If your DSR is too high (usually above 60-70%), banks will reject your property loan application. This is why you should avoid buying expensive cars before buying a house.
Does FAR Academy teach property investment to absolute beginners?
Yes! FAR Academy is designed specifically for newbies and young business owners. We provide step-by-step guidance in simple, easy-to-understand language so you can confidently buy your first property without making costly mistakes.

